Second Chance Checking Accounts and Their Real Limitations
Second-chance accounts restore basic banking, but fees and limits come with them.
Most people never hear the name ChexSystems until a bank turns them down, yet it controls access to everyday banking the same way a credit bureau controls access to a loan. ChexSystems is a consumer reporting agency that tracks banking history rather than credit history: overdrafts, unpaid fees, accounts a bank closed involuntarily, and suspected fraud all land on the record. A strong credit score buys no protection here.
The system works on a numeric scale, and the scale explains why banking feels inconsistent from one bank to the next. ChexSystems assigns each consumer a score between 100 and 899, but no single cutoff applies across the industry, because every bank picks its own threshold for what counts as too risky. That's why the same person, with the exact same file, can get rejected at one bank and approved at another a few blocks away. There's no universal pass or fail. There's only what a particular bank decided to tolerate.
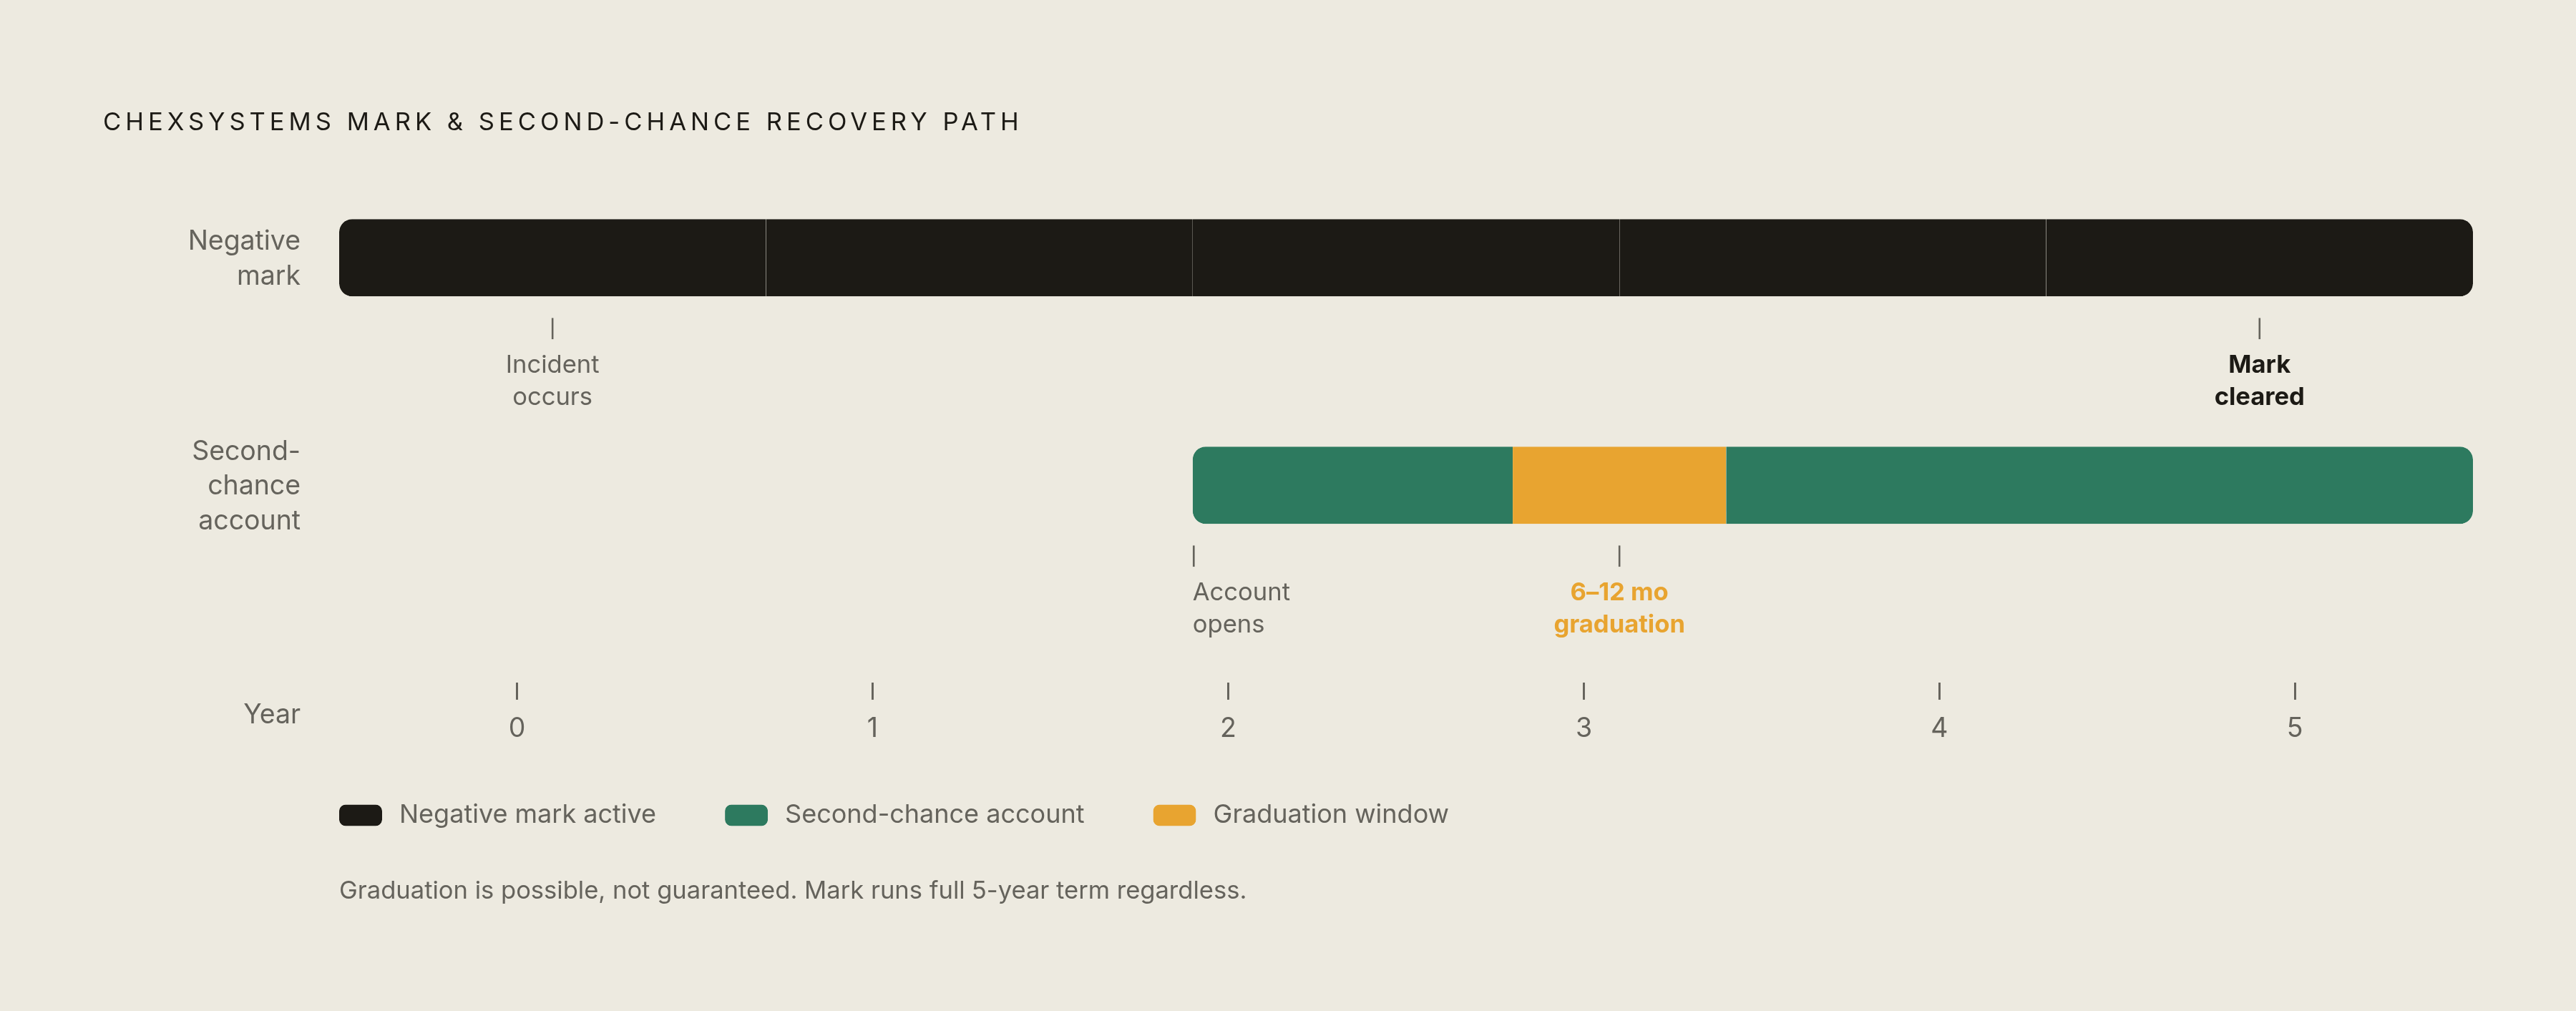
The timeline makes the damage last. A negative mark, whether it's an unpaid overdraft or an account a bank shut down without the customer's say, stays on the report for five years. One rough stretch, maybe a job loss or a medical bill that drained an account, can follow someone for half a decade, long after the actual financial situation has recovered.
The weight of this system doesn't fall evenly. Low-income consumers, minorities, and people who have never held an account before carry the heaviest burden, in part because the normal requirements for opening an account, a minimum deposit, or specific ID documents, sit on top of whatever ChexSystems already holds against them. This gap appears in the numbers: the Federal Reserve's Economic Well-Being report found that roughly one in every seventeen U.S. adults had no bank account at all in 2025, a rate that hasn't moved since 2021 and that stays concentrated among younger adults and among Black and Hispanic adults.
What second-chance checking accounts provide
Second-chance accounts exist to undo exactly that kind of exclusion. They hand back the basic tools of modern financial life that being unbanked takes away, and that handoff carries real, practical weight. A second-chance account typically keeps the core features intact: a debit card, direct deposit, online and mobile banking, ATM access, and the ability to deposit checks, enough to function in an economy that has mostly stopped taking cash. None of that is a small convenience. It's the baseline infrastructure most people assume everyone has.
There's a protection angle too, one that's easy to overlook. For someone who has been locked out of the banking system, that protection is a meaningful upgrade over managing money in cash or through other informal means. A second-chance account also cuts the need for check-cashing storefronts and money orders, both of which charge their own fees and offer no protection on the money handed over.
These accounts aren't just a parking spot either. Using one responsibly builds a positive ChexSystems record over time, and that record can open the door back to a standard account, often somewhere between six and twelve months of clean activity, depending on the bank. The account becomes a repair tool as well as a workaround.
The market for these accounts has grown wide enough that comparison shopping actually makes sense. National banks, regional banks, online banks, and credit unions all offer some version of a second-chance account, so a consumer who's shopping around can weigh fees and features against each other rather than settling for the single option in front of them. Chime® Checking charges no monthly maintenance fee, no overdraft fee, requires no minimum balance and no minimum deposit to open, and gives access to more than 47,000 fee-free ATMs, though it carries no interest and no physical branch network. Chase Secure Banking℠ needs no minimum opening deposit and charges a low monthly service fee that's waived for account holders aged 17 to 24 or for anyone meeting a qualifying electronic deposit threshold each statement period. It skips overdraft fees by declining transactions outright rather than covering them, offers no interest, doesn't issue paper checks, and doesn't reimburse out-of-network ATM fees, though it comes with a large branch and ATM network and new accounts are currently eligible for a cash bonus after a set number of qualifying transactions within a set enrollment window, an offer that expires. Woodforest National Bank's Second Chance Checking may require an in-branch visit to open, serves states across the South, Midwest, Mid-Atlantic, and East Coast, charges a monthly fee that depends on whether direct deposit is set up, and asks for a $25 minimum deposit. Gold Coast Federal Credit Union's Fresh Start Checking charges a monthly fee and needs no minimum deposit on the checking account itself, though membership requires opening a separate Main Share savings account with its own minimum. Credit Union 1's Second Chance Checking charges no monthly fee and asks for no minimum deposit to open.
What these accounts cost in practice, and what they structurally cannot do, deserves just as much attention before anyone treats one as a full substitute for standard banking.
The structural trade-offs built into second-chance accounts that most descriptions understate
Second-chance accounts are not a cheaper or slightly stripped-down version of a standard checking account. They are a different product built around a different purpose, risk management instead of convenience, and the trade-offs that come with that purpose are predictable.
Start with the monthly fee, because it's the most visible cost. Bankrate's research puts these fees commonly somewhere in the single digits up to the low double digits, and unlike standard checking, where waiving the fee through direct deposit or a minimum balance is routine, many second-chance accounts offer no way to waive it at all. Some charge notably more than that range and don't even issue a debit card or checks in return. Then there's the overdraft rule, which gets marketed as a benefit: no overdraft fee, because the transaction simply gets declined instead of covered. That protects against a spiraling fee, but it also means a forgotten charge, a bill that hits a day early, or a subscription nobody remembered signing up for can bounce a transaction on the very account someone opened to prove they can manage money responsibly.
Writing a check isn't a given either. Wells Fargo's Clear Access Banking, among other second-chance products, doesn't support check writing at all, which becomes a real problem for rent payments or any payee who won't take an electronic transfer. Some accounts also cap how much a debit card can spend or withdraw in a day, below what a standard account would allow, which shrinks the account's usefulness for a big purchase or a sudden emergency. Interest, even the token amount many standard checking accounts pay, is missing from most second-chance products entirely.
None of this erases the five-year shadow described earlier. Opening a second-chance account doesn't wipe a negative ChexSystems item off the record. It stays for its full five-year term no matter how carefully the new account is handled. The new account builds a positive history going forward, but it doesn't undo what came before it. And graduation to a standard account, while possible after six to twelve months of responsible use at many institutions, isn't guaranteed or universal. It depends entirely on which bank holds the account.
None of these limits are design flaws. They're the predictable shape of a product built to manage risk for both the bank and the customer, and a consumer who expects a second-chance account to behave like a standard one is set up for a bad surprise.
The passive finance problem for second-chance account holders
The very features that make second-chance accounts safer on paper, no overdraft buffer, hard caps on spending, turn ordinary financial inattention into something far riskier than it would be for a standard account holder.
Think about what happens with a forgotten streaming subscription. For someone with a standard checking account, that charge might trigger an overdraft fee, annoying but recoverable. For someone on a second-chance account running close to a balance limit, the same charge gets declined outright, and a declined transaction is exactly the kind of event that damages the positive ChexSystems history the account was supposed to be building. The margin for error simply isn't there.
Bill creep makes this worse: it is not a single mistake but an ongoing condition. Promotional prices expire, fees get raised quietly, service tiers get renamed, and none of it announces itself. Catching it takes sustained attention that most people don't have the bandwidth to maintain. A 2026 example documented by BillCreep.com shows the pattern clearly: a family of four paying for mobile service watched their line access fees and a bundled streaming package each climb by roughly a third over two years. A household on a standard account can absorb that kind of drift without much trouble. A second-chance account holder with a tight balance ceiling has almost no room to absorb it at all.
This problem shows up across the broader economy in enforcement actions. A 2025 settlement tied to Amazon's Prime enrollment practices totaled billions of dollars, combining a civil penalty with a large consumer redress fund, and as of September 2026, Amazon had already paid out more than $845 million of that redress to consumers. Those were dark-pattern sign-up practices that pulled people into subscriptions they didn't mean to keep, at a scale large enough to require a federal settlement. A second-chance account holder who lets a free trial convert without noticing, or misses a quiet price hike on a subscription, risks a declined card at the worst possible moment, or a negative balance that locks out all debit card use and withdrawals entirely, the way the U.S. Bank Safe Debit Account is built to do. The account's own safety mechanism becomes the thing that punishes the inattention.
What second-chance account holders can claim back
Consumers managing tight account balances have more legitimate ways to recover money than most of them ever use. The gap is about who knows these programs exist and who follows through on claiming them, not about who qualifies.
Price-drop policies are one example, and they vary enough by retailer that most shoppers never bother to track them. The Microsoft Store offers a one-time price adjustment on physical products if the price drops within a set window after delivery, with an extended window during the holidays. Target refunds the difference if a lower price appears within its own ecosystem, meaning Target.com, a physical Target store, or the Target app, within a set period after purchase. Amazon doesn't run a formal, universal price-adjustment policy, but there are workarounds: asking for a goodwill credit through customer chat, or returning an item and repurchasing it at the lower price within the standard 30-day return window.
Late-delivery credits sit in the same unclaimed category. Major carriers and retailers run guarantee programs that trigger a refund or a credit when a shipment arrives late, and almost none of them get claimed, simply because nobody is watching the shipping status closely enough after an order goes out. The same applies to refunds that get promised but never arrive, duplicate charges that slip through, and subscriptions that keep billing after a cancellation request goes through. All of that is money genuinely owed back to the consumer, and it usually goes unclaimed only because the charge or the missing refund never gets noticed.
For someone managing a second-chance account, recovering even a modest amount through a price-drop claim or a missed delivery credit can shift the balance enough to matter. That small amount of headroom can keep a transaction from being declined.
Why manual monitoring isn't realistic for most people
These recovery options go unclaimed because catching them requires constant, active attention that almost nobody sustains on top of work, family, and the rest of daily life.
Every one of these opportunities runs on its own clock. Price-drop windows, free-trial conversion dates, late-delivery credit deadlines, and subscription price hikes all follow different timelines and different trigger conditions depending on the retailer or the service. Tracking all of that by hand, across a typical household's full set of accounts and subscriptions, adds up to something closer to a full-time job than a weekend chore.
The research on subscription spending backs this up. Consumers aren't ignoring their subscriptions because they don't care. They genuinely don't know what they're paying, and the gap between what people estimate they spend and what they actually spend each month shows just how wide that blind spot runs. The real obstacle is that the information needed to catch any of it sits scattered across bank statements, email receipts, and a handful of different app stores, in a form that makes spotting the pattern almost impossible without pulling it all into one place.
Sources
- Second Chance Checking - Zing Credit Union
- Second Chance Checking Accounts: What They Are and How They Work | One Smart Dollar
- What is Second Chance Banking and Second Chance Checking? | Chase
- wellsfargo.com
- 10 Best Second Chance Checking Accounts of August 2026
- What Is Second Chance Banking?
- wtop.com
- creditunion1.org